
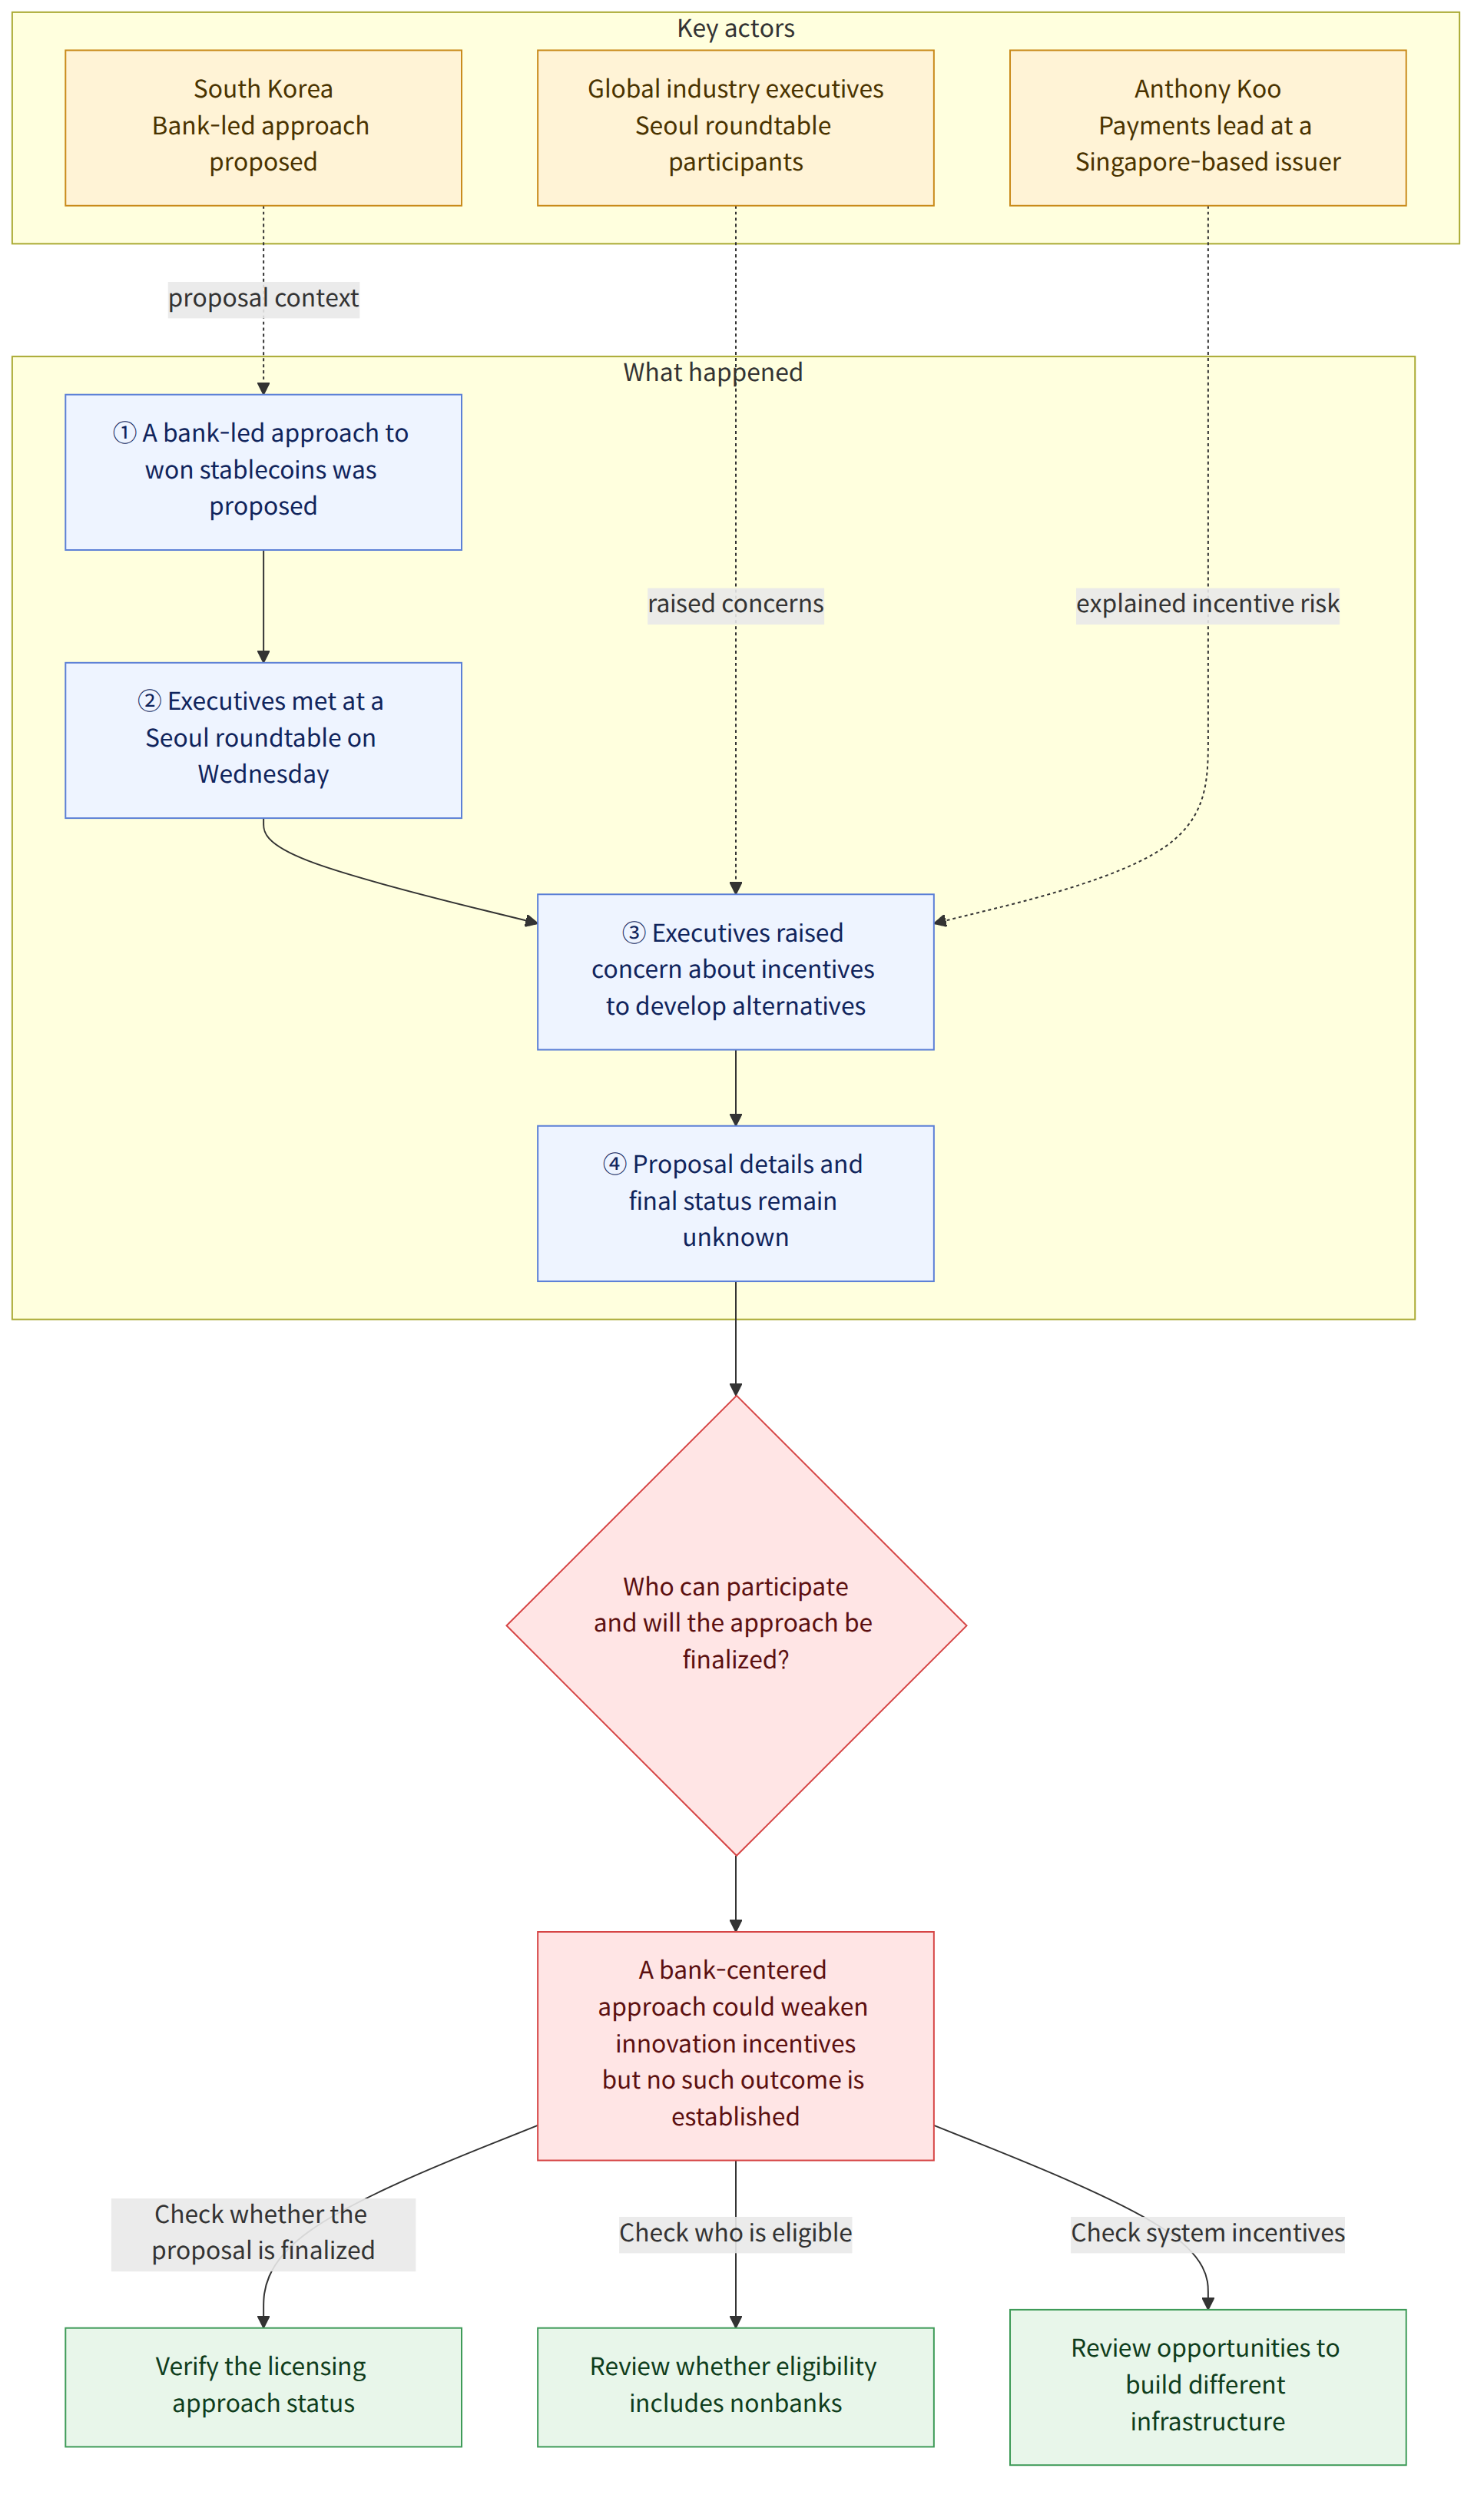
Industry concerns have emerged that designing a bank-centered licensing system for won-based stablecoins could limit innovation. Global industry executives who attended a roundtable in Seoul on Wednesday said institutions with existing payment networks might have little incentive to actively develop alternatives.
Background and context
In South Korea, a bank-led approach to won-based stablecoins has been proposed. A stablecoin is a digital asset designed to have its value pegged to a specific asset or currency.
Anthony Koo, who leads payments at a Singapore-based stablecoin issuer, said regulators tend to grant licenses to Tier 1 banks. He explained that licensing banks could give them less incentive than fintech companies to build infrastructure and push the boundaries of existing systems.
What this means
The issue is not only whether banks should be licensed, but also which types of institutions can participate and how the system can be designed to motivate them to build infrastructure that differs from existing payment networks. The industry executives’ concerns raise the possibility that a bank-led approach could weaken competition and innovation; they do not establish that such an outcome has occurred.
For example, if a bank with an existing payment network received a license, it might have less incentive than a fintech company to develop new infrastructure or push the boundaries of existing systems, according to Koo. This is an illustrative scenario based on the industry’s concern, not a statement about the actual plans of any particular bank or fintech company.
What is confirmed and what remains unknown
Confirmed facts
- A bank-led approach to won-based stablecoins has been proposed in South Korea.
- Global industry executives raised concerns about the risk that a bank-led approach could limit innovation at a Seoul roundtable on Wednesday.
- They said institutions with existing payment networks might have less incentive to develop alternatives.
- Anthony Koo was identified as the head of payments at a Singapore-based stablecoin issuer.
What remains unknown
- What are the specific details of the won stablecoin licensing proposal?
- Have the authorities finalized a bank-centered licensing approach?
- What is the name of the stablecoin issuer Anthony Koo works for?
What readers should check
- It is worth checking whether the relevant licensing approach is still at the proposal stage or has been finalized.
- The specific requirements should be reviewed to see whether eligibility is limited to banks or includes other types of institutions.
- If the system is finalized, it will also be worth checking what opportunities and incentives it provides for institutions to build infrastructure that differs from existing payment networks.

















