A Race Against Time
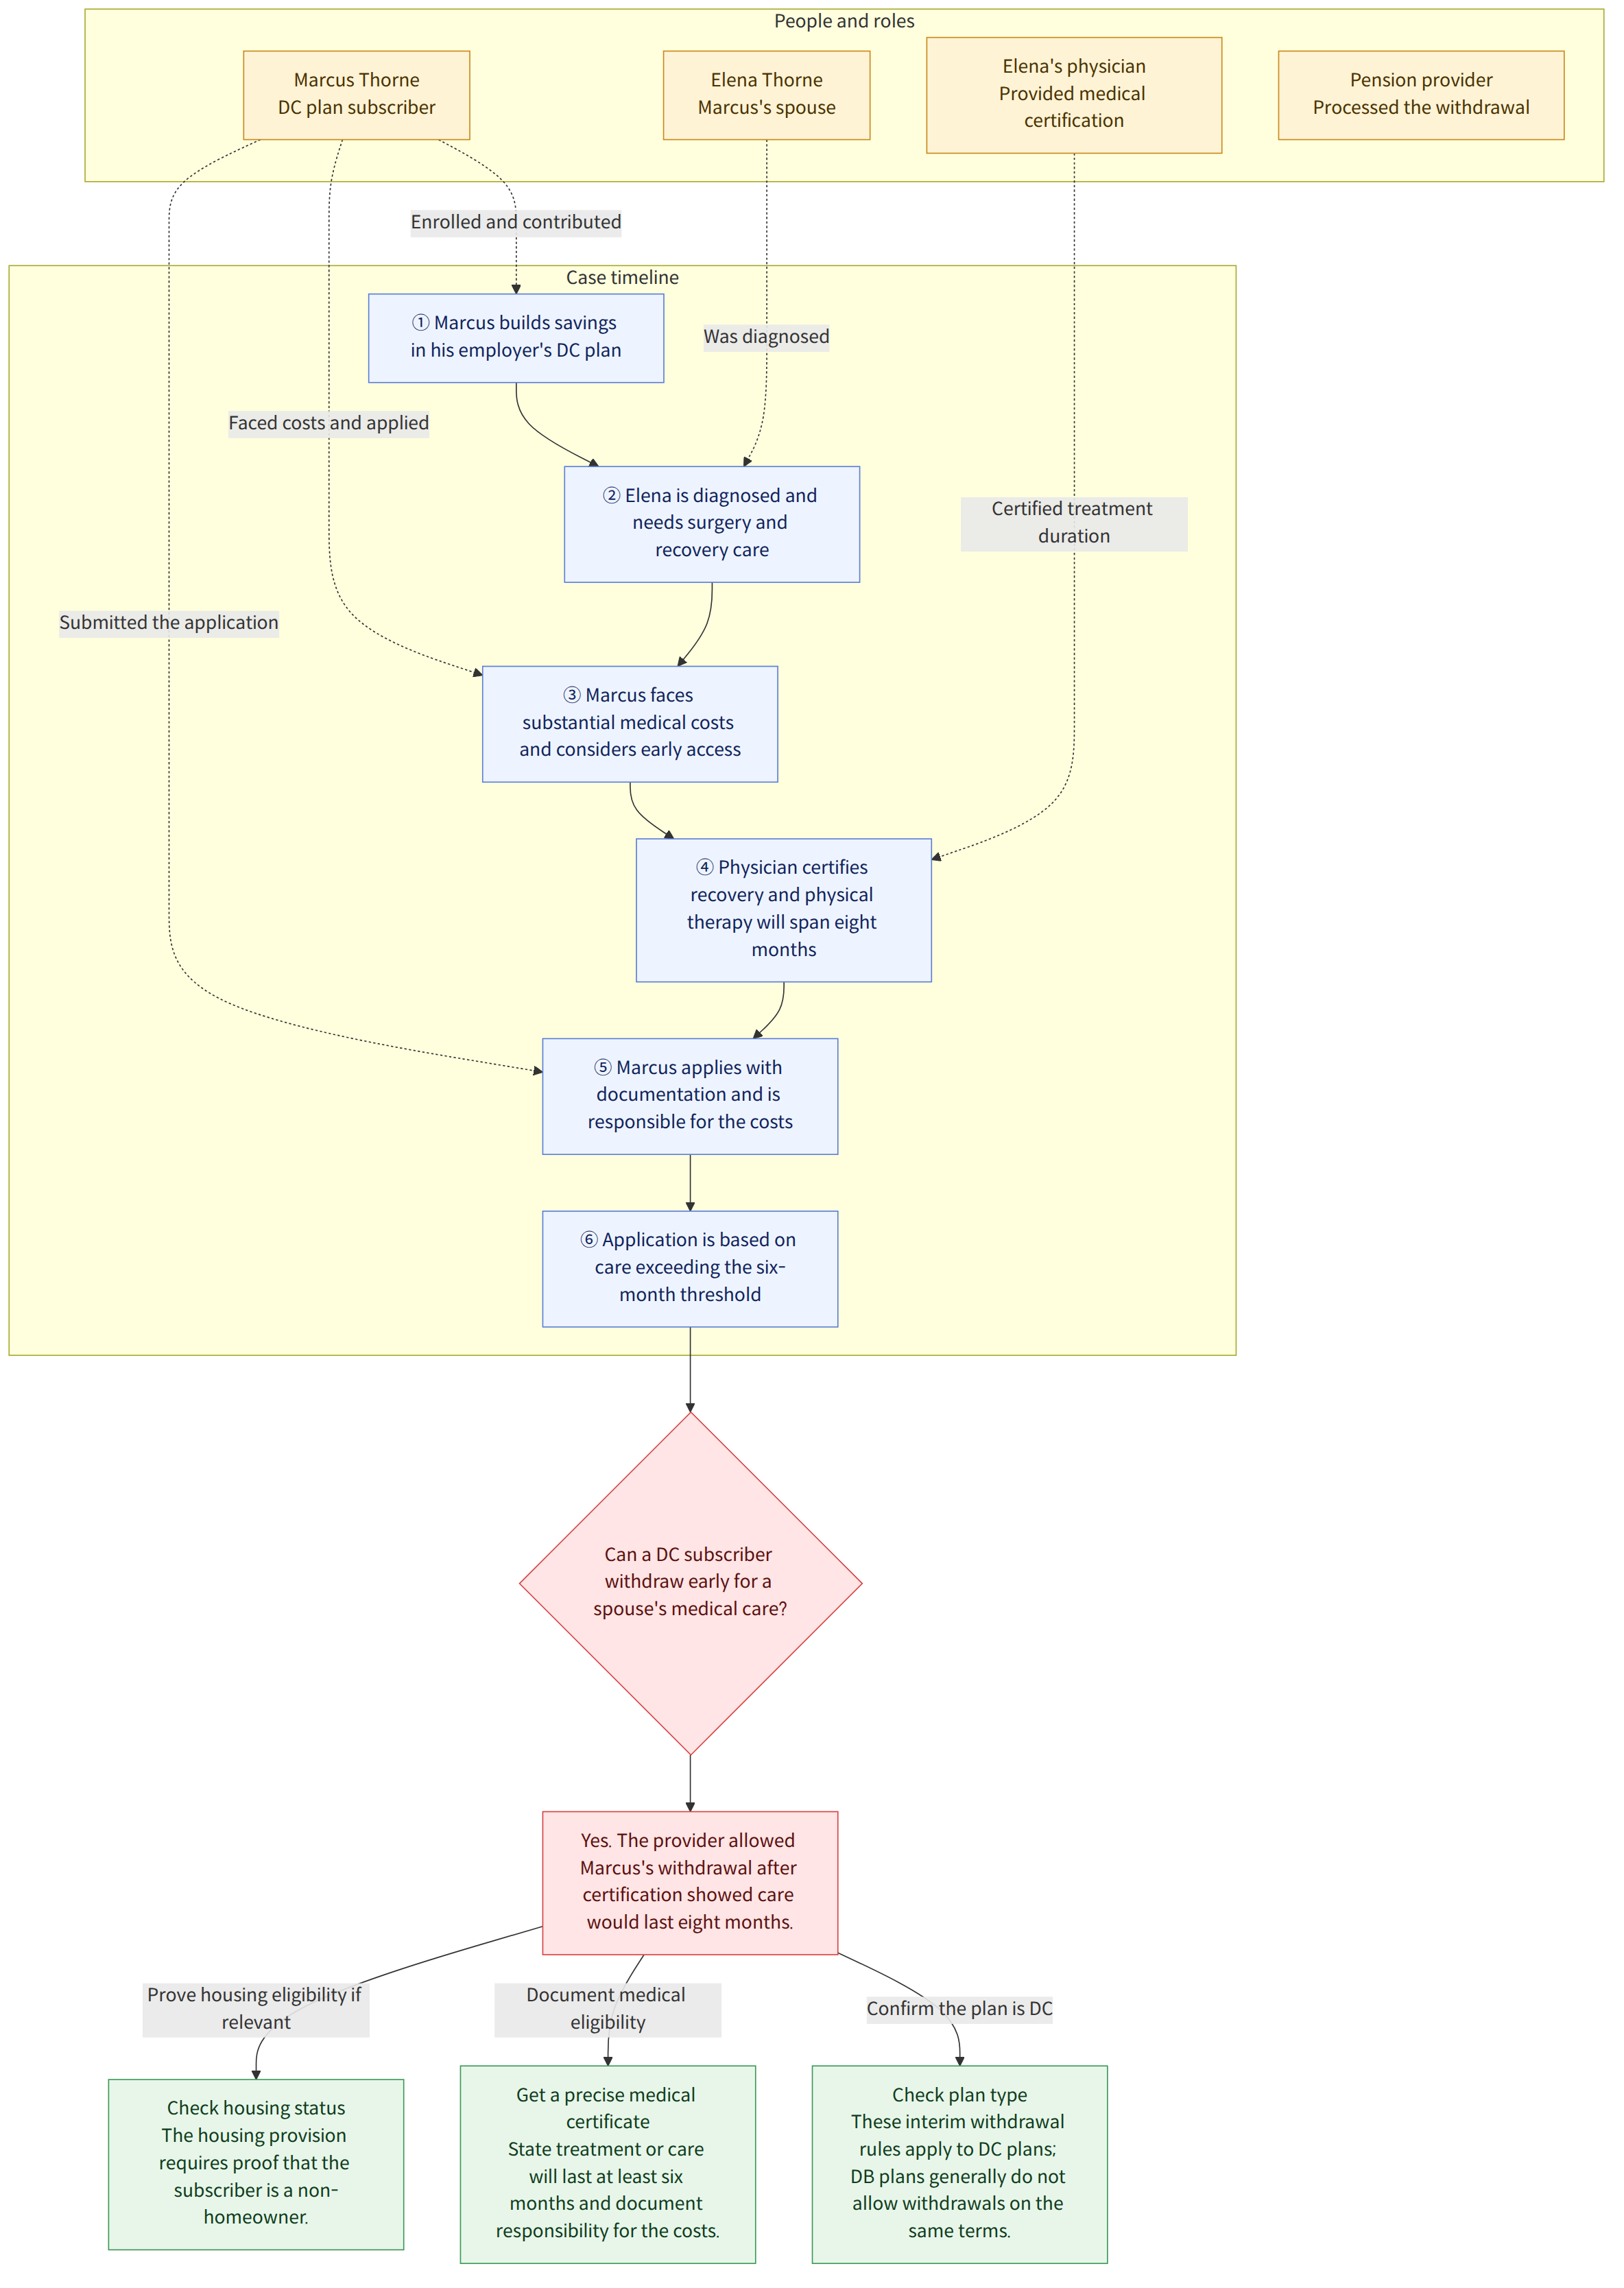
Marcus Thorne had spent seven years building a stable career at a leading tech firm in Seoul. He was a diligent employee, and his company utilized a Defined Contribution (DC) retirement pension plan, where contributions were steadily accumulating for his future. Life was predictable until a sudden, devastating diagnosis hit his wife, Elena.
Elena was diagnosed with a severe condition requiring a complex, expensive surgery and a prolonged recovery period. While they had insurance, the out-of-pocket costs for the specialized treatment and the subsequent rehabilitation were staggering. Faced with a mounting hospital bill and the stress of Elena's health, Marcus looked at his retirement account. He didn't want to touch his future savings, but the urgency of the present left him with no choice. He wondered if there was any legal way to pull those funds out without resigning from his job.
The Legal Question
Can an employee enrolled in a Defined Contribution (DC) retirement pension plan legally withdraw their accumulated funds prematurely to cover the medical expenses of a spouse?
What Korean Law Says
Under the Employee Retirement Benefit Security Act and its accompanying Enforcement Decree, retirement pensions are designed to be preserved until the employee actually retires. However, the law recognizes that certain life-altering crises require immediate liquidity.
According to Article 22 of the Act and Article 14 of the Enforcement Decree, early withdrawal (interim payment) is permitted only under specific conditions, including:
- Housing Needs: When a non-homeowner subscriber purchases a home in their own name or pays a deposit for a lease (limited to once per employer).
- Medical Emergencies: When the subscriber, their spouse, or a dependent requires medical treatment for a disease or injury for six months or more, and the subscriber is responsible for the costs.
- Financial Distress: When the subscriber has been declared bankrupt or has entered a personal rehabilitation process within the last five years.
- Natural Disasters: Other reasons designated by the Minister of Employment and Labor, such as severe damage from natural disasters.
How Korean Courts Approach This
Korean courts and regulatory bodies strictly interpret these requirements. Because the fundamental purpose of the retirement pension is to ensure old-age stability, early withdrawals are treated as an exception rather than a right.
The courts emphasize the objective evidence of the necessity. For medical withdrawals, the key is not simply that a surgery is "expensive," but that the condition requires a prolonged period of care (the "six-month rule"). If the medical necessity is proven through a doctor's diagnosis and certification, the request for withdrawal is generally granted.
Applying the Law to the Case
In Marcus's situation, the legality of his withdrawal depends on the nature of Elena's recovery.
- The Relationship: Elena is Marcus's spouse, which satisfies the familial requirement of the law.
- The Financial Burden: Marcus is the primary provider responsible for the medical costs.
- The Duration of Care: This is the critical factor. If Elena's surgery and subsequent rehabilitation are expected to require medical care for six months or more, Marcus meets the legal threshold for an interim withdrawal.
If Marcus can provide a medical certificate stating that Elena requires long-term treatment exceeding six months, the pension provider must allow the withdrawal of the funds.
Conclusion: What Happened, and What Should You Do?
Fortunately, Elena's physician provided a detailed diagnosis confirming that her recovery and physical therapy would span eight months. Armed with this documentation, Marcus successfully applied for an early withdrawal from his DC plan, allowing him to pay for the surgery and ensure Elena received the best possible care without the crushing weight of immediate debt.
Practical Advice for Readers:
- Verify Your Plan Type: Remember that these early withdrawal rules apply to DC (Defined Contribution) plans. DB (Defined Benefit) plans generally do not allow interim withdrawals under the same terms.
- Get a Precise Medical Certificate: If applying for medical reasons, ensure the doctor's note explicitly mentions the duration of treatment (e.g., "requires treatment/care for more than 6 months").
- Check Your Housing Status: If you are using the housing provision, ensure you have documentation proving you are a non-homeowner, as this is a strict prerequisite.